Announcing our SOC2 Type 2 Compliance.
Categories
Blog INSIGHTS

The Power of Branding for Financial Advisors: Standing Out in a Crowded Market

In today’s competitive financial services landscape, branding is more crucial than ever for financial advisors. As Sheri Fitts, a prominent figure in the industry, aptly puts it, “You have a brand whether you are intentional about it or not.” But what exactly is a brand, and why is it so important for financial advisors?

Why is a Brand Important?

Your brand is more than just what you do or how well you do it—it’s the essence of who you are, how you want to be perceived, and the values you represent. In an era of commoditization and consolidation, a strong brand is often the key differentiator that sets you apart from the competition.

Lessons from Iconic Brands

Consider the world’s most valuable brands like Apple, Google, and Amazon. While financial advisors may not aspire to reach such global recognition, the principles behind their branding success can be applied on a smaller scale. The goal is to create a brand that resonates with your target audience and stands out in your local market.

For financial advisors, branding operates on multiple levels:

  1. Your organization (if you’re part of one)
  2. Your colleagues and associates
  3. Your personal brand

Building a strong personal brand is about consistently demonstrating your expertise and commitment to your clients’ financial futures. By offering comprehensive solutions like estate planning through your own branded portal, you reinforce the value you bring to your clients. Every service you provide and every interaction you have helps shape a well-rounded and trusted brand image.

Building Your Brand with OneDigitalTrust

At OneDigitalTrust, we understand the critical role branding plays in helping financial advisors stand out. That’s why our platform offers advisors the unique opportunity to brand our financial advisor portal and estate planning tools as their own. This customization allows you to present a powerful suite of estate planning tools directly under your personal or business brand.

By offering branded estate planning services through our portal, financial advisors can significantly elevate their value proposition. Instead of being seen solely as a financial advisor, your clients will now recognize you as a trusted advisor who manages all aspects of their financial well-being, including estate planning.This deepens client relationships and solidifies your brand as an all-encompassing financial solution provider.

How Branding with OneDigitalTrust Differentiates You

In a crowded marketplace, differentiation is key. Financial advisors who offer branded estate planning services can position themselves as forward-thinking and client-focused. Through the OneDigitalTrust platform, you can seamlessly integrate estate planning into your existing services, reinforcing your brand as an innovator who cares for your clients’ entire financial future—including their estate.

Strengthening Client Loyalty and Growing Referrals

A strong brand creates lasting impressions, not just by delivering excellent services, but by how it makes clients feel. Advisors who use branded estate planning services not only provide more value but are also seen as thought leaders who are ahead of the curve. This builds trust, increases loyalty, and generates word-of-mouth referrals.

As more clients seek integrated financial and estate planning solutions, offering these services under your own brand can also open up new revenue streams without adding significant workload. It’s a simple yet powerful way to expand your practice.

Taking Control of Your Brand

At the end of the day, your brand is what will set you apart in a highly competitive field. By intentionally building and controlling your brand, you can secure stronger client relationships, more referrals, and a more resilient practice. Through OneDigitalTrust’s platform, you can ensure your brand isn’t just known for financial advice—it’s known for comprehensive, personalized financial solutions.

So, the question isn’t whether you have a brand—you do. The real question is: are you leveraging the full potential of your brand? Let us help you strengthen your brand today with our customizable, advisor-branded estate planning platform.

Categories
Blog INSIGHTS

The Power of Pet Trusts in Estate Planning

In today’s world, pets are more than just animals – they’re beloved family members. As financial advisors and institutions, it’s crucial to recognize the growing importance of pet care in estate planning. Our platform offers a seamless way to create pet trusts, ensuring your clients’ furry friends are cared for even when they can’t be there.

Why Pet Trusts Matter More Than Ever

Pet ownership in the U.S. has surged, with approximately 70% of households owning a pet, according to a 2023-2024 survey conducted by the American Pet Products Association (APPA). As more families welcome pets into their lives, informal pet care arrangements no longer provide sufficient security. Without a plan, many pets face abandonment, ending up in shelters. In fact, the ASPCA reports that approximately 1 million pets are euthanized each year due to a lack of homes or care.

Legally binding pet trusts provide the peace of mind that pet owners need, knowing their animals will receive proper care according to their wishes. Pet trusts secure financial provisions for everything from daily care to veterinary expenses, and owners can specify detailed instructions to ensure their pets maintain their accustomed level of care. Offering solutions like pet trusts is essential for any comprehensive estate plan to ensure the safety and well-being of pets, preventing them from being left in precarious situations.

Unique Support with ASPCA Pet Care Calculator

What sets our platform apart is the inclusion of the ASPCA’s pet care calculator, which simplifies the process by providing cost estimates for pet care. This feature relieves clients from having to come up with figures on their own, ensuring they allocate the appropriate funds for their pets’ needs. By offering precise estimates, advisors and clients can create more accurate and effective pet trusts.

Why This Feature Is Essential

Integrating pet trust creation into your estate planning services isn’t just a trend—it’s a necessity. With the growing number of pets being considered family members, offering this service demonstrates a commitment to addressing every aspect of your clients’ estate needs. Without this option, your clients may feel their plans are incomplete and seek services elsewhere that accommodate their pets.

Our platform simplifies the pet trust creation process, ensuring that financial advisors can easily offer this critical service. The efficiency of our customizable templates, combined with the ASPCA pet care calculator, means you can add pet trusts to your offerings without significantly increasing your workload.

Unlock New Opportunities

By offering pet trust services, you not only help clients protect their pets but also open new doors for your practice. The growing demand for pet-inclusive estate planning creates new revenue streams, stronger client relationships, and differentiation in a competitive market. Don’t miss the chance to enhance your services with this increasingly necessary feature.

Ready to take your estate planning services to the next level? Contact us today for a demo of our pet trust creation feature – complete with the ASPCA pet care calculator – and offer truly comprehensive estate planning for every family member, furry ones included!

Categories
Blog INSIGHTS

Preserving the Life-Legacy for clients and members: The Sentimental Side of Estate Planning

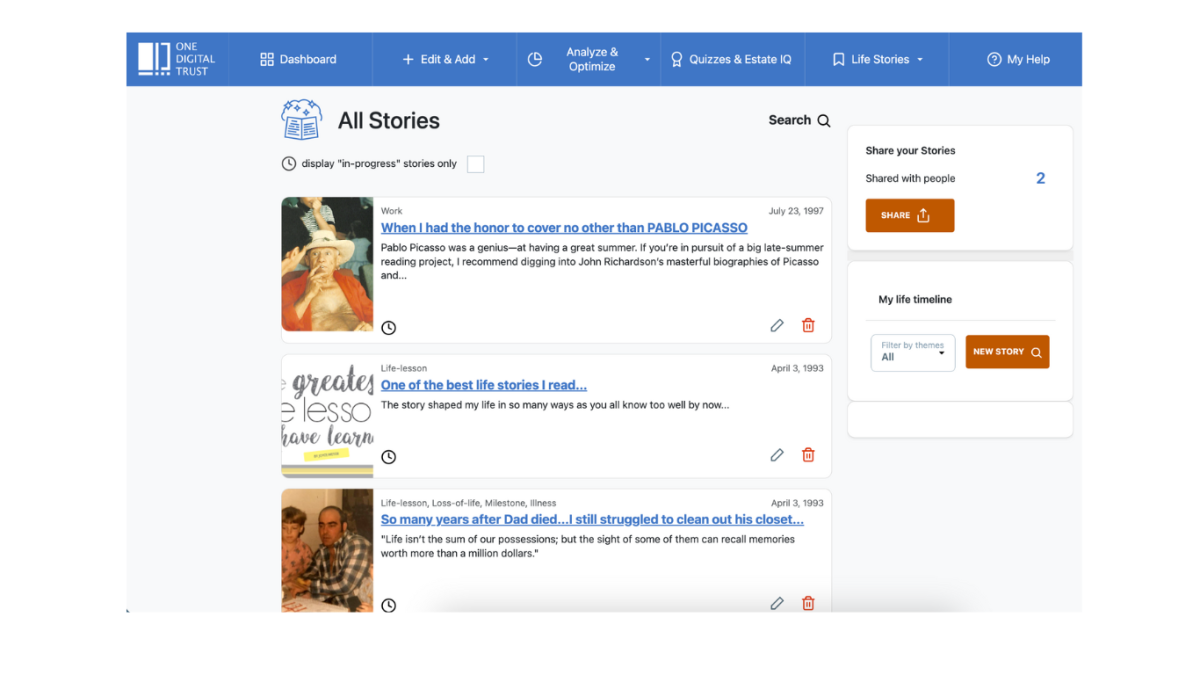
When discussing estate planning with clients and members, the focus often centers on assets, wills, and legal documents. However, the stories, values, and experiences that define their lives are equally important. Our estate planning platform’s Life Stories feature addresses this often-overlooked aspect of legacy planning, allowing your clients and members to capture and express bite-sized versions of key life experiences to share with future generations. 

A Window into Their World

The Life Stories feature enables your clients and members to create short narratives about their most memorable life experiences. But it doesn’t stop there. They can enrich these stories with audio, video, and images, bringing their memories to life in vivid detail. Your clients and members can share amazing memories such as:

  • The story of how they met their spouse, complete with a recording of their favorite song
  • A recounting of their proudest achievement, accompanied by photos of the event
  • The history behind a family heirloom, showcased in a video with a detailed explanation of its significance

These multimedia stories create a rich, immersive experience for their loved ones, allowing them to connect with these memories on a deeper level.

Why Sentimentality Matters in Estate Planning

In traditional estate planning, sentimentality is often overlooked, yet it’s this emotional connection that truly resonates with heirs. Encouraging the expression of sentimentality is essential because these stories, values, and emotions transform an estate plan from just a set of legal documents into a cherished legacy. When individuals preserve these priceless memories, they’re not just protecting their history—they’re strengthening emotional bonds. As a financial advisor or institution, offering this opportunity sets you apart, demonstrating a deep commitment to the emotional and financial well-being of those you serve. This deeper connection enhances your service, strengthening relationships and bolstering your brand’s reputation.

A Digital Altar for Immortalizing Memories

The OneDigitalTrust platform is uniquely equipped to help achieve this sentimentality through an integrated feature that serves as a digital altar—a memorial where memories are immortalized. It’s more than just a repository for stories; it’s a sacred space where legacies live on, accessible to future generations. This exclusive capability transforms estate planning into a deeply personal experience for your clients and members, ensuring that stories, values, and emotions are preserved in a meaningful and lasting way.

Beyond Assets: The Value of Values

While financial assets are undoubtedly crucial, the true essence of estate planning lies in preserving and transmitting values, wisdom, and life lessons. The Life Stories feature helps clients and members to:

  1. Provide context: Stories can explain the reasoning behind certain financial decisions or bequests, helping heirs understand these choices.
  2. Share wisdom: Life advice, family traditions, or personal philosophies that have guided someone can be passed down.
  3. Preserve family history: Anecdotes about ancestors or family lore that might otherwise be lost to time can be recorded.
  4. Express love and appreciation: Messages can be left for loved ones, sharing feelings and the impact these individuals have had.
  5. Inspire future generations: Stories of perseverance, achievement, or personal growth can motivate and guide descendants.

Sentiments Enrich Estate Planning

While the traditional elements of estate planning remain vital, the sentimental aspect should not be underestimated. Personal stories are the threads that weave together the tapestry of a client’s life, and sharing them is perhaps the most precious legacy they can leave behind.

The Life Stories feature on the OneDigitalTrust platform makes it easy for your clients and members to capture, enrich, and share these invaluable memories, ensuring that their values, experiences, and wisdom live on for generations. By offering this unique, integrated service, your firm not only elevates its offerings but also strengthens client relationships, positioning you as a leader in comprehensive and compassionate estate planning.

Categories
Blog INSIGHTS

National Make-A-Will Month: Dispelling Myths and Strengthening Client Relationships

For financial advisors and financial institutions, National Make-A-Will Month offers a unique opportunity to deepen client and member relationships, provide valuable guidance, and enhance your brand by incorporating estate planning into your services. With our Financial Advisor portal, you can easily guide clients through the estate planning process, helping them create or update their Wills. This not only strengthens your relationships but also positions you as a comprehensive financial advisor. With 68% of Americans without a Will, this month serves as a reminder to your clients and members to take action.

Myth: Only the Wealthy Need Estate Plans

Reality: Estate planning is essential for clients and members at all income levels. Advising clients and members to protect their assets, no matter the size, ensures their wishes are honored and legal complications are minimized.

Myth: Estate Planning Is a One-Time Event

Reality: Clients and members often think estate planning is a once-and-done task. In reality, it requires ongoing review and updates as life circumstances change, such as marriage, divorce, or the acquisition of new assets, etc.

Myth: Estate Planning Has to Be Expensive

Reality: With the OneDigitalTrust platform, we offer comprehensive estate planning to your clients and members without the hefty price tag. With transparent costs and a user-friendly interface, we can ensure they will get the best value for their investment.

Myth: Clients Don’t Ask Advisors About Estate Planning

Reality: Research shows that 93% of clients expect estate planning advice from their financial advisor, but only 22% receive it. Also, 66% of children change financial advisors after inheriting wealth. OneDigitalTrust strengthens client relationships and uncovers new opportunities.

As we observe National Make-A-Will Month, it’s the perfect time to reinforce the importance of estate planning to your clients and members. By dispelling myths and offering accessible, effective solutions like the OneDigitalTrust platform, you can help ensure that everyone, regardless of wealth or stage in life, has a plan in place. Let’s use this opportunity to build stronger, more informed relationships with those we serve, and make a meaningful impact on their financial well-being.

Categories
Blog INSIGHTS

How the financial advisory space has evolved

By Guest Blogger Doug Trott, director & advisor to SaaS and fintech firms

Well, I have been advising wealth management businesses ranging from discount brokerage to private banking for more than three decades now.

One of the most significant changes, indeed, pressures on the financial advisory space has been the advent and success of self-directed, typically discount, brokerage offerings. This may seem like ‘old news,’ but the effects on the industry and investors have been profound and unfolded over decades.

As retail investors became empowered by firms like Schwab and Fidelity, their expectations around value for fees from advisors increased substantially. With the subsequent introduction of the internet, investors could conduct investment research and analysis, compare alternative investments and ideas, and construct portfolios, which had historically been the purview of financial advisors.

Second, the ‘advertised’ price of trades caused many investors to question the cost of investment services delivered by advisors, leading to fee compression and a need to upskill advisors. During this period, mutual funds exploded in popularity and adoption, soon followed by exchange-traded funds.

These developments empowered investors, increased their investment choices, and reduced their investment costs. Advances in technology not only empowered investors but also further empowered advisors. Most recently, the introduction of managed ETF portfolios and then robo-advisors further broadened investor choice and lowered the reference price of investments, amounting to further price pressure on advisors.

As these fundamental changes occurred, advisor business models began to shift, with firms like LPL and other ‘independents’ enabling advisors to effectively rent a leading-edge technology platform and operate as their own business, defining their individual service offering, product ranges and price levels. As a consequence, there has been a steady shift of advisors from employed advisors to independent advisors. At the same time, the industry as a whole sees few firms hiring and training new advisors, so the pool is shrinking as advisors retire.

Where people get their financial advisory services

A positive outcome of the growth of tech platform availability has been the empowerment of credit unions and community banks to provide competitive investment offerings to their members and clients, representing an increase in competition.

We have also witnessed the steady introduction of regulations designed to protect retail investors, many of which have the unintended consequence of burdening firms and advisors and representing significant demands on the time and capacity of advisors to remain compliant. Many would argue that retail clients are better protected but at a cost reflected in the increased expense of investment delivery and the compression of time available for advisors to serve their clients.

Product innovation has accelerated with the gradual adoption of alternative investments and digital assets, changing the complexion of investment portfolios and introducing new demands on advisors.

Lastly, and most recently, the advent of tech solutions that enable ‘hyper-personalization’ has improved the nature of the client relationship, shifting from one-size-fits-all to customized plans and even service models.

To be sure, the financial advice industry has evolved mainly for the betterment of retail investors. Their product choice has broadened. They can choose to be self-directed, advised or both. They can choose from a wide range of low-cost to full-service offerings, and their regulatory protections have increased. Indeed, one could argue they now suffer from too much choice and too much protection.

The confluence of COVID-19

The COVID-19 pandemic was a massive jolt to the industry. Uncertainty after the S&P declined 19.4% at the start of the pandemic had clients asking questions and advisors overwhelmed by those seeking answers to the risk they were now experiencing. To compound matters, face-to-face meetings became extinct quickly, precipitating clients’ adoption of digital communication methods faster than advisors, their firms and regulators had ever contemplated.

After enabling remote work and catching up to client digital expectations, financial advice firms invested in creating fully digital experiences and redesigning their compliance processes to accommodate a new service experience. The financial planning market – long considered a paper-document-heavy, arduous, unpleasant experience where more than half of clients failed to complete what they and their advisor started – was rejuvenated by dozens of innovative new tech firms that launched digital-first applications designed to be client – rather than output – centric.

COVID-19 also got people thinking about mortality and estate planning

The pandemic also increased the propensity of clients to consider end-of-life planning as loved ones faced the risk of prolonged illness or even death.

Lately, executives and individual advisors have become increasingly concerned as they appreciate the import of a looming asset transition among family members. Historical experience has shown that when a client dies, and their estate is administered, the heirs and beneficiaries most typically exit the incumbent advisor relationship, thereby reducing their assets under administration and earnings stream.

Over the last few years, a shift has occurred to discard the notion that this attrition is unavoidable and that there is a payoff to becoming proactive about advice delivery beyond the lifespan of the individual client. Pundits hypothesize that the causes of the attrition are a lack of advisor familiarity with the heirs and beneficiaries, non-involvement with the estate administration, and unintended exclusion of heirs and beneficiaries from the client relationship.

In response, advisors have increasingly sought methods to address these causes, largely to become more fully aware of the estate and its heirs and beneficiaries and be regarded as a resource by those constituents. OneDigitalTrust allows financial advisors to see more deeply into clients’ complete financial assets, including those held elsewhere, and the beneficiaries to begin to develop an ongoing relationship with them far into the future.

Historically, advisors referred their clients with more complex and large potential estates to local attorneys or in-house trust departments in the case of wire houses and banks. They often lost control and visibility of the process and the likely outcomes. These referrals typically represent less than 10% of the clients; the rest of their clients remained in an ambiguous state – attorneys were too costly, and they were considered too small to be served by internal trust departments.

Fintech to the rescue

Enter financial technology innovators to address the question: How do we use technology and scale to generate cost-effective estate documents and advisor visibility for advisors’ unserved clients? Fintechs have invested substantial capital into designing processes and easy-to-use software that simplifies the process, customizes it for all legal jurisdictions, and enables advisors to collaborate with their clients instead of referring them ‘out of house’ all the while safeguarding that there is no “unauthorized practice of law.”

Clients who lack estate plan documents can now build confidence that their plans and wishes are documented and stored in a secure digital vault, that they will be alerted to any changes that require changes, and that their documents will be readily accessible to their estate plan executors, all at a reasonable cost.

Clients with estate documents can benefit from the digital vault and change-required alerts. Advisors gain full visibility into the estate components, deepen their client relationships, become relevant to the future heirs and beneficiaries, enable an efficient periodic estate review, and add a new revenue stream to their business.

The OneDigitalTrust platform’s simple user interface and guidance ensures an individual’s estate is optimized for probate, delivering the most value to the family. And, finally, we pass on so much more than money: Whether it’s your grandad’s life story or your great aunt’s chicken soup recipe, it can be passed down along their the decedent’s possessions with OneDigitalTrust.

By adding estate planning to their services, financial advisors:

  • Gain complete visibility into the financial and non-financial assets of the client
  • Enable relevant engagement with future heirs, beneficiaries, and executors, thereby reducing the prospect of future attrition
  • Add a tech-enabled touchpoint with clients to review the estate plans’ currency and affect any changes required
  • Add a new recurring revenue stream to their practice

In the words of Nike, “Just do it!”

Categories
Blog INSIGHTS

From Management Consultant to Entrepreneur, Sonny Kapoor Finds Opportunity in Estate Planning

CEO Sonny Kapoor and co-founder Rocky Mehta founded OneDigitalTrust, a pioneering digital estate planning platform, to spare families the stress and strain of dealing with the costly and time-consuming process of a loved one dying intestate, or without completing their estate planning.

Through their own experiences, they tapped into a little-known opportunity to address the needs of the mass affluent who are underserved in this area. Many believe it’s too costly to be worthwhile, and others don’t think they have enough of an estate to worry about.

Sonny sat down with Sarah Snell Cooke, co-founder of The Credit Union Connection, to share insights into his mission, vision and B2B model for OneDigitalTrust.

Sarah Snell Cooke: What’s the origin story of OneDigitalTrust?

Sonny Kapoor: I have worked as a management consultant for financial institutions for many years. During an engagement to overhaul the strategy for a credit union-owned RIA (Retirement Investment Advisor), we proposed digital estate planning as a new, innovative offering with the potential to deepen family and financial wellness for members.

The recommendation received much acceptance, but instead of building it themselves, the institution asked if I would build it so they could license it. And OneDigitalTrust was born.

The challenge of designing a platform that would be simple and affordable especially resonated with me because my father died intestate when I was 17 years old. I experienced first-hand the challenges my mother and I encountered in settling his estate, working through age-old estate planning laws.

SSC: Why are people not completing their estate planning? What’s the problem with that?

SK: Why such a remarkable proportion of the U.S. citizenry does not have a legally valid plan in place is a complex question. Up to this point, the easy answer was that the process was expensive and cumbersome.

This issue should be materially addressed with the advent of digital estate planning platforms like OneDigitalTrust. Yet, between 2023 and 2024, a 6% decline was recorded in Americans with an estate plan.

The more complex answer is buried in the deep psyche –estate planning makes individuals confront their mortality. Nobody welcomes the anxiety that accompanies such a task. Much of the avoidance is due to mortality salience – an awareness of the inevitability of one’s death creating anxiety, which triggers a powerful defense mechanism to side-step such thoughts (e.g., trivializing one’s likelihood of death or amplifying one’s ability to boost longevity, etc.). As a result, thoughts about our death are banned from persisting in our awareness and estate planning remains de-prioritized.

SSC: Who is OneDigitalTrust’s target audience? Why did you choose B2B?

SK: Our platform is intended for use by the mass affluent – all of those who do have some assets to pass down but suffer sticker shock at the lawyer’s fees or don’t even know where to start. Many don’t realize the thousands – or tens of thousands of dollars and more – that can be lost to a family legacy when someone dies intestate (without an estate plan).

Our platform streamlines the process, removing complexity through a custom-built, proprietary design, to offer affordable estate planning to many who never thought it would be within their means. We’ve lowered the barriers to entry to both price and users being overwhelmed by the complexity of it. OneDigitalTrust has built-in features to help users optimize their probate exposure so that more assets go into their beneficiaries’ pockets.

With so many – more than 65% – avoiding planning their estates, it’s crucial that we get our platform out to as many people as possible. This is why we decided to leverage a B2B, or business-to-business structure and sales model. By partnering with banks and credit unions, financial advisory firms, wealth management companies, insurance agencies and employee benefits companies, OneDigitalTrust can quickly touch many more families’ lives to save them from the head- and heartache my mother and I endured.

Digital estate planning is an ideal offering for institutions that desire to deepen the value of their own brand. Since estate planning goes to the very core of personal and family wellness, our B2B capability allows institutions to offer it as their service.  As a result, users credit the brand of their trusted provider with the peace of mind they feel when they complete their plan. This amplifies the brand loyalty for the institution like very few other offerings can.  Further, it is through our unique B2B partnering model that we can offer institutions a real option to generate a new non-interest income revenue stream to counterbalance the fee income that the Consumer Financial Protection Bureau and others are chiseling away.

SSC: How does OneDigitalTrust connect with companies to offer your platform?

SK: At one level, we have integration partnerships, such as Mastercard/Finicity, Zillow and others, that enrich the capability and functionality of our platform. We’ve also partnered with leading digital banking platform providers, like Jack Henry, Q2, Temenos and more, including proprietary integrations to embed OneDigitalTrust in their clients’ digital banking experiences. There’s no heavy lifting required for banks and credit unions; within days, they can reap the rewards of developing even more meaningful relationships with their customers and members.

SSC: What are the benefits to the institutions you partner with and serve (credit unions/banks/financial advisors/law firms/benefits providers/insurance companies)?

 SK: First, we are a B2B solution provider. Our objective is to focus on deepening our partners’ brand instead of promoting the OneDigitalTrust brand. Our powerful white-label capabilities deliver exceedingly well on that objective.

Second, unlike referral models, we offer our partners the ability to garner an exceedingly healthy margin while keeping the platform highly affordable for end-users. This helps our financial institution customers generate a durable new revenue stream to offset the loss of overdraft and debit interchange non-interest income that’s been slowly eroding.

Third, our customers can deliver an essential, highly desirable end-of-life planning capability to safeguard the legacy of their customers and members – quite literally, everyone needs an individual plan.

And finally, our partnering model extends beyond platform enablement. Our Partner Success team helps customers with ongoing support, from custom implementation playbooks to data analysis to sharing and cataloging best practices to webinars and training to various marketing support activities to measure and monitor utilization and performance.

Financial institutions are often seen as slow to adapt and less tech-savvy than fintechs. By partnering with an innovative platform like OneDigitalTrust, banks and credit unions can break free from that reputation and bring more attractive services to younger customers and members.

SSC: Any final comments or thoughts?

SK: Humans have an instinctive and ongoing existential fear of death. This ‘death anxiety’ can create cognitive distortion, which makes people act irrationally, such as putting off essential estate planning. The paradox is that having completed their estate plan, the same individuals reduce the intensity of such death anxiety and amplify personal and family well-being enormously. We believe financial institutions are best suited to deliver estate planning to their customers so they can deepen their brand among the communities they serve.

Categories
Blog INSIGHTS

Cracking the Code: How to Help Mass Affluent Clients Embrace DIY and Advisor-Assisted Estate Planning

Many financial advisors, particularly those serving clients through credit unions and community banks, face a challenge: how to effectively engage the “mass affluent” market.

These folks have a household income of at least $75,000 and liquid assets of between $100,000 and $1 million. They comprise one-quarter of our nation’s population.

They are the middle class and the sweet spot for financial advisors. Their numbers are significant, and they are primed for advisors to help them build for retirement and end-of-life planning. Effective, efficient estate planning will cement their personal legacy for their loved ones and cherished causes, as well as reduce unnecessary hassles for their families after they pass.

One key to unlocking this market lies in dispelling a common myth: top-shelf financial planning is reserved for the high-net-worth crowd.

You’re in an ideal position to extend your financial institution’s status as a trusted preferred financial institution (PFI) beyond savings and loans into investing and estate planning. And you can combine high tech and high touch by mixing do-it-yourself digital and face-to-face interaction to pull it all together. Let’s discuss how.

The Power of Small Steps in Estate Planning

Think back to the countless times you’ve encountered a client hesitant to begin investing because they don’t believe they have enough to make it worthwhile. You likely countered with the power of compounding interest, demonstrating how even small, regular contributions can grow substantially over time.

The same principles of starting early and building in small increments apply here, also. That begins with dispelling their misconception that estate planning necessitates a complex web of trusts and other legal documents.

The reality is that a fundamental plan—a will, beneficiary designations on accounts, and perhaps a power of attorney—can provide a strong foundation for the mass affluent. And they can accomplish this for a fraction of the cost they might have thought.

Here are some solid steps to follow:

  • Compounding Clarity: Frame estate planning as a way to safeguard their legacy. Just like consistent investments grow over time, a clear plan provides long-term peace of mind for them and their loved ones.

Start by guiding clients through all the people they’d like included in their estate planning. For a basic will, they can assign percentages, and it’s pretty much done. And, within OneDigitalTrust’s platform, your clients can always convert to a custom will or trust later. Custom wills can get very granular into who receives what when the family member passes.

  • Start with the Basics: Highlight the importance of having a will or basic trust, even for those with a seemingly straightforward financial picture. Explain how that ensures their wishes are followed and avoids potential family conflict during a difficult time.
  • Small Steps, Big Impact: Emphasize that simply starting is a crucial first step. As their wealth and life circumstances evolve, they can easily adapt the plan on their own or with your help as their trusted financial advisor. If they convert to a custom will or revocable trust, they can adapt beneficiaries and inheritances as desired.

Digital Tools Empower DIY and Advisor-Assisted Planning

As with banking and investing, technology has revolutionized estate planning, making it more accessible and affordable for the mass affluent. Tools like OneDigitalTrust’s digital estate planning platform empower clients to take control of their wishes while offering valuable opportunities for advisor involvement.

Here’s how these tools can benefit both you and your clients:

  • Client Empowerment: Digital platforms guide clients through creating a basic estate plan, fostering a sense of control and understanding.
  • Increased Accessibility: OneDigitalTrust’s tools are available 24/7, allowing clients to work on their plans at their own pace and convenience.
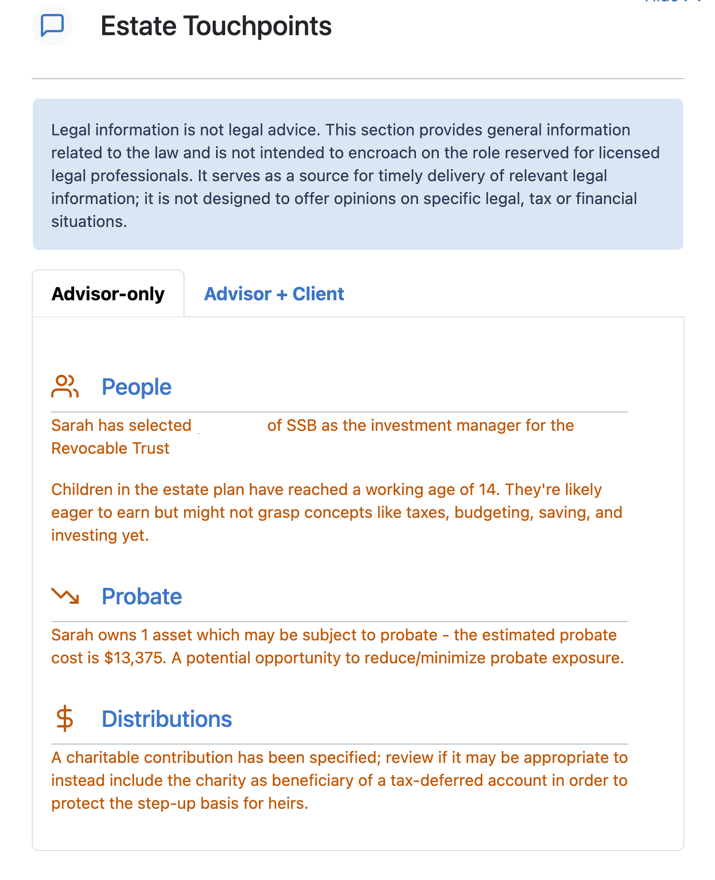
  • Enhanced Communication: Digital platforms can facilitate communication between you and your clients, allowing for clarification of questions and updates to the plan as needed. Inside our Advisor Portal, financial advisors receive nuggets of vetted advice to share with their clients, making you look sharp and building even more trust that you’re on their side.

estate planning touchpoints image

Positioning Yourself as the Trusted Guide

While DIY tools empower clients, it’s crucial to position yourself as the trusted advisor who complements the technology. Here are ways to leverage your expertise:

  • Review and Refine: Offer to review a client’s DIY plan, ensuring it aligns with their specific goals and circumstances.
  • Tax and Legal Nuances: Explain how even a basic plan can benefit from the guidance on tax implications and potential legal complexities.
  • Complexities and Future Needs: Discuss situations where a DIY approach may not suffice, and clients should follow your and OneDigitalTrust’s guidance when the need for more sophisticated planning arises.

Over time, your trusted relationship with your client will build, and based on your experience with them and others, you’ll see opportunities and pitfalls for them that you can then share and advise, creating opportunities for deeper service and upselling.

Unlocking the Mass Affluent Market

Remember, the cornerstone of successful financial planning is building trust and empowering clients to take control of their financial future.

By offering a combination of accessible technology and your expert guidance, you can become their go-to for helping them build, enjoy and then pass on their financial legacy, one well-informed step at a time.

170M Americans need an estate plan. OneDigitalTrust offers a white-label, turnkey estate planning platform with pricing options tailored to the needs of individual credit unions and financial advisors.

Contact us today to learn more!

Categories
Blog INSIGHTS

Digital Estate Planning Rounds Out Financial Advisors’ Wheelhouse

The estate planning process is daunting on an emotional and practical level. It’s also costly, with a maze of legal documentation and pricey lawyers. Digital estate planning tools are revolutionizing the field; they offer a more accessible, streamlined and cost-effective approach for financial advisors to guide their clients.

For financial advisors taking on estate planning, your clients benefit from a simplified process and reduced costs. Still, these tools also empower financial advisors to deepen their engagement by providing more holistic, life-long services through the end of the individual’s personal financial journey.

Unveiling the Benefits: Efficiency, Affordability, and Accuracy

Digital estate planning platforms like OneDigitalTrust deftly use technology to expedite the procedure and provide numerous significant benefits.

First, it eliminates the necessity for drawn-out legal consultations. Digital platforms help users identify and classify physical and digital assets, everything from gold bars to cryptocurrency. Robust platforms like OneDigitalTrust seamlessly use that data to produce personalized legal documents, like power of attorney directives, wills, trusts and even sharing of life stories, guaranteeing their finances and their legacy are securely recorded for the next generation.

Second, digital estate planning offers significant cost savings over traditional estate planning, which can deter people from taking the necessary steps. Digital platforms typically charge a subscription fee or a one-time flat fee, making the process far more affordable. This allows a broader range of individuals to secure their legacies without breaking the bank.

Third, digital platforms allow the user to create accurate and clear documents. OneDigitalTrust’s platform produces documents at about a 10th grade reading level without compromising the legal veracity. Of course, as their trusted advisor, you can provide a seamless digital experience for your clients and, as necessary, help guide them through the process. Employing a systematic approach and state templates, these technologies reduce the possibility of mistakes or omissions that often afflict these documents. This helps ensure a more seamless transfer of assets following the death of a loved one.

The Advisor’s Evolving Role: From Investments to Invaluable Guidance

Importantly, your advisory can offer digital estate planning to keep your financial advisors in your client’s entire wealth management process rather than handing them off to an attorney and never hearing anything more about it. While these platforms can automate much of the process, complexities still arise, and your relationship and expertise can make you a hero.

Financial advisors are well-versed in all aspects of their clients’ financial circumstances, including insurance plans, retirement accounts and investment portfolios. Digital estate planning tools are critical to making an advisor’s services more comprehensive with limited additional time commitment.

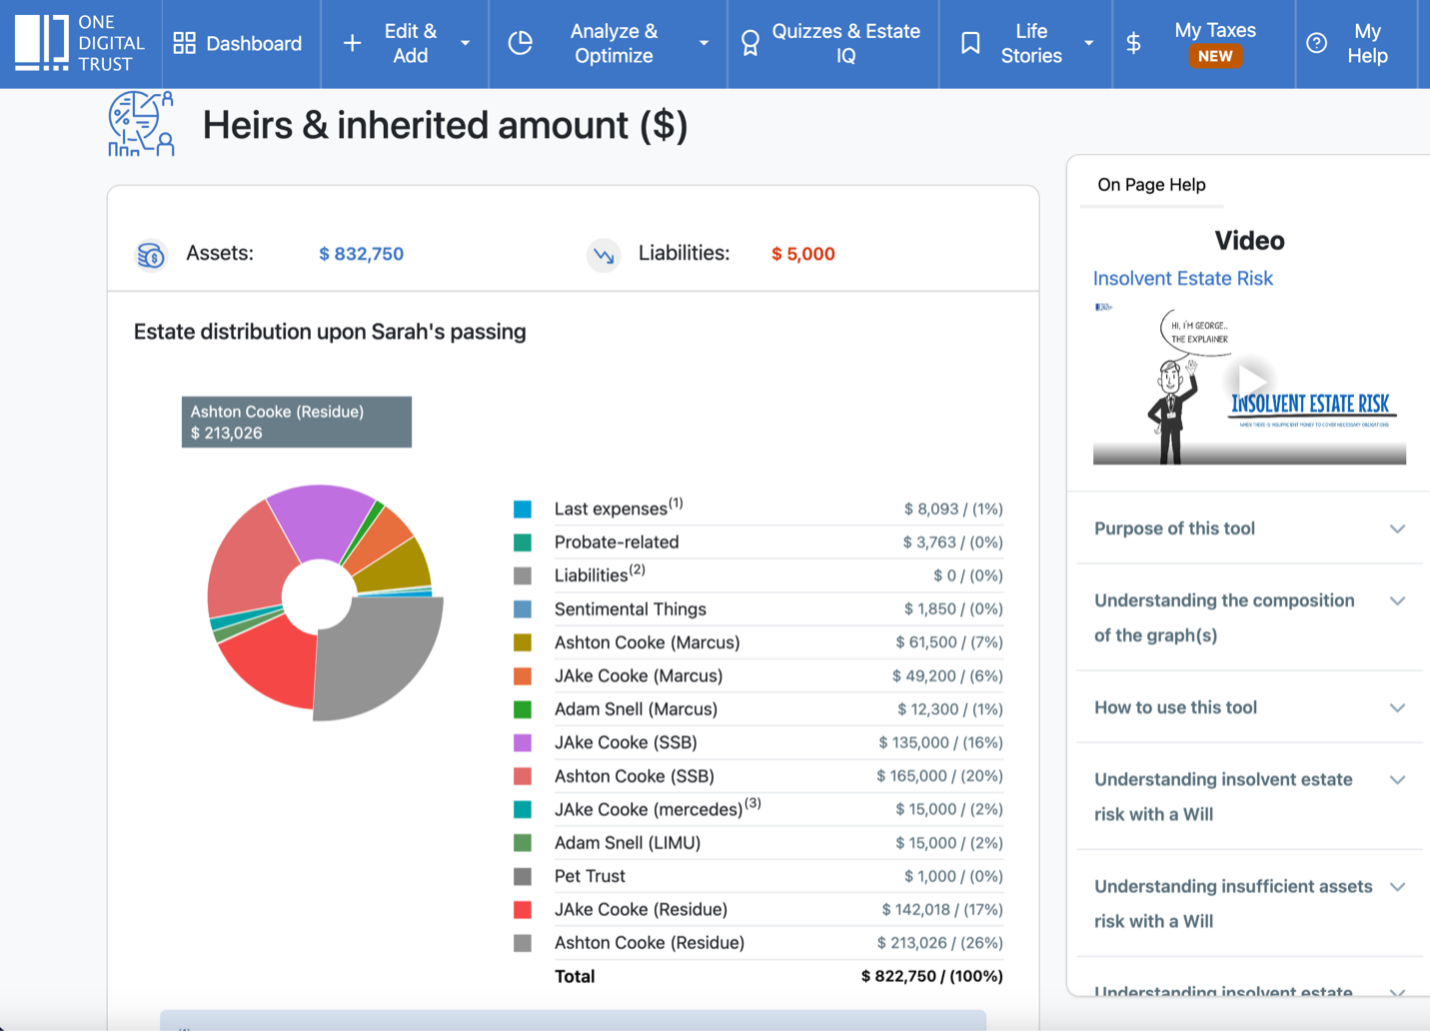
OneDigitalTrust can help record beneficiary designations by asset, which are available in a visual waterfall of the distribution of assets. Our Financial Advisors portal helps financial advisors engage customers in a meaningful dialogue that supports their long-term financial outcomes and demonstrates tremendous added value with little effort on the advisor’s part.

By initiating and continuing discussions about digital legacies, advisors can foster trust and demonstrate their commitment to a client’s long-term well-being. This strengthens the bond between advisor and client, positioning the advisor as a trusted confidant – not just a trusted financial manager.

The Financial Advantage: New Revenue Streams and Client Retention

Financial advisors have much to gain from digital estate planning. Advisors and their employers can tap new services, glean additional data on their clients, and even help prevent elder financial abuse through OneDigitalTrust’s estate planning platform.

Moreover, digital estate planning fosters client retention. Clients who receive comprehensive financial planning, including digital legacy management, are more likely to maintain a long-term relationship with their advisor, boosting the chances of keeping that relationship with the next generation. This capability bolsters the advisor and the organization’s reputation as a comprehensive wealth management solutions provider.

Ultimately, OneDigitalTrust’s digital estate planning solution enables advisers to increase their value by streamlining the procedure, saving members and customers money, and guaranteeing safe and correct legacy records.

Financial advisors who leverage modern technology can establish themselves as trustworthy in the digital world as it rapidly evolves, creating new revenue sources and building stronger client relationships.

170M Americans need an estate plan. OneDigitalTrust offers a white-label, turnkey estate planning platform with pricing options tailored to the needs of individual credit unions and financial advisors.

Contact us today to learn more!

Categories
Blog INSIGHTS

3 Rs to Prevent Elderly Financial Abuse: Red Flags, Relationships and Respect

Consider financial education comprehensively for National Financial Literacy Month

Recent lawsuits point to both the vulnerability of many older Americans to the scourge of online financial fraud and the opportunity that engaged financial services providers have to help thwart such pernicious crime.

Two such complaints are against a top 5 bank, which is accused of allowing two elderly women in California to lose more than $2 million to so-called “pig butchering scams.” Here, fraudsters posed as IRS agents to win the victims’ trust and trick them into multiple fraudulent transactions facilitated by the bank.

In another case, a top bank and credit union are accused of making 75 international transfers—74 of them alone through the credit union—by a retired naval officer totaling about $3.6 million. Unfortunately, many transfers were made even after concerns were explicitly reported to adult protective services in the officer’s home county.

The AARP says an estimated $28.3 billion is lost to what it calls elderly financial exploitation (EFE) each year in this country. Some 72% is lost to people the victims know, such as friends and family.

The emotional toll includes embarrassment and anguish and so much more, including, as in the California cases mentioned above, a person losing not only her life’s savings but also her home. Financial services providers are on the frontline in detecting and preventing this criminality, which targets the growing elderly population.

April is National Financial Literacy Month, and it can’t stop at teaching young children to save and spend their allowances wisely. We must consider financial education more holistically. So, what can a responsible, proactive bank, credit union, financial advisor, wealth manager or other financial services provider do?

Red Flags

First, make sure protocols to safeguard elderly clients are standard operating procedure. That begins with training staff to recognize red flags. Those can include unusual withdrawals or Not Sufficient Fund occurrences, newly added co-owners on accounts, or sudden investment decisions inconsistent with a client’s known objectives.

Indicators of the latter can include senior clients receiving excessive phone calls or visitors pushing dubious financial arrangements. Another indicator is a sudden change in beneficiaries and other terms in the consumer’s estate planning.

Relationship Building

Uncovering such situations requires an engaged relationship with the potential victims, combining a personal and digital touch. Financial services providers should initiate internal reviews and documentation when suspicion arises from unusual account activity. A best practice is assigning a dedicated team to investigate thoroughly. Potential steps include discussing concerns with the client privately, reviewing the legitimacy of transactions, and scrutinizing relationships with any new parties acting on the client’s behalf.

Again, that requires a trusted relationship with the member or customer and the determination to act. If your internal investigation uncovers likely malicious activity, cutting off access to the accounts and reporting your concerns to the appropriate authorities is imperative. State adult services, law enforcement and the Consumer Financial Protection Bureau all have protocols for EFE cases. Become part of the solution.

Respecting Privacy While Protecting Everyone

We stress again that it takes an engaged relationship with the older adult and their family to be in a position to discover elderly financial exploitation. And, the digital capabilities of OneDigitalTrust’s platform are designed to undertake the heavy lifting for financial advisors to be aware of certain estate planning-related actions or events that imply potential financial elder abuse, like taking advantage of probable incapacitation or undue influence.

OneDigitalTrust empowers financial services clients to safely digitize and share estate documents, impact analysis, account information, and powers of attorney with a pre-approved network of family members and trusted advisors, such as financial planners.

We need to add that while vigilance is essential, you must balance privacy and client preferences against protecting them and your own institution’s interests and liability.

Indeed, there can be a fine line between doing too little and doing too much, between inaction and overstepping institutional authority. Digital services facilitate transparency and shared access to respect that shifting, evolving line and comfort zone for you and your clients.

Indeed, OneDigitalTrust can be a critical component of the seamless collaboration between clients, family members, financial advisors and other legal and medical professionals, which results in the best decisions regarding elderly welfare and assets.

This heightened visibility also reduces exploitation opportunities while honoring client desires for privacy and autonomy. The OneDigitalTrust platform brings elderly individuals’ entire advisory team into a secure, unified digital space where abnormalities or suspicious activities become readily apparent.

Elderly financial exploitation will always be with us, but proactive identification and coordinated interventions can curb its effect on your clients and your institution. Staff training, documented and followed escalation procedures, aggressive reporting of suspected crimes, and selective account freezes can disrupt fraudsters and protect your most valuable assets: the people who entrust you with their money, dignity and financial independence. Make relationship building, recognizing red flags and reporting elderly financial exploitation part of your National Financial Literacy Month celebrations in April.

170M Americans need an estate plan. OneDigitalTrust offers a white-label, turnkey estate planning platform with pricing options tailored to the needs of individual credit unions and financial advisors.

Contact us today to learn more!

Categories
Blog INSIGHTS

Break the Habit: Digital Estate Planning as an Essential Tool and Differentiator

The time and complexities involved in providing estate planning have long made it an outlier as a service. Investment advisors and wealth managers at traditional credit unions, banks, insurers and other financial services providers have been relegated to the sidelines as they refer their clients, customers and members to attorneys, as is the typical practice.

That practice, however, is changing as financial services continue to rapidly evolve in the digital world. Your organization will no longer have to pass your consumers—as well as the income they can generate—on to lawyers, keeping you from deepening those relationships.

Virtual estate planning platforms have been hard at work, developing their digital muscles, eradicating the need for attorneys, and even in-person servicing if an individual chooses. Empower your firm to break the habit of making third-party referrals and to deepen the personal touch and value they build with their clients, helping those they serve to navigate their financial lives and plan their legacies more holistically.

A Hybrid Advisor-Client Experience

“A streamlined digital estate planning platform delivered as a hybrid advisor-client experience provides a unique opportunity for advisors to expand their service model, amplify relationship alpha, power retention, and create advisory pathways to the next generation of clients,” a new report from Javelin Advisory Services reads.

Titled “Digital Estate Planning: A New Frontier for RIAs,” the think tank’s report focuses on the power of digitizing the creation and storage of relatively simple but vitally important documents such as wills, revocable trusts, and medical directives. It cites OneDigitalTrust as a leader in creating that new nexus of advancing fintech innovation and growing advisor value, as shown in the illustration below.

Javelin Research found OneDigitalTrust to provide advisors innovation and value.

The Relationship Alpha for The Next Aging Generation

Millennials have surpassed baby boomers as the largest generation in the United States. Those 20-somethings to 40-somethings are digital natives. They’re accustomed to living online – including working, shopping, learning, and banking – but they’re still real, live human beings, naturally, who can benefit from professional guidance and advice through their journeys.

Along with traditional matters such as raising families, forging and maintaining careers, caring for aging relatives, and the vicissitudes of aging, they also find themselves with their own unique set of stressors, as the Javelin report astutely illustrates in this figure below.

Platforms like OneDigitalTrust help to calm financial services providers clients' anxiety, Javelin found.

The “Demographics” section in the above figure includes “increased personal wealth,” among other factors that present an opportunity to RIAs and other financial services providers who can most seamlessly and effectively combine high-tech and high touch for this cohort of adult Americans.

As the report observes, all these factors imply that scaled delivery of personalized solutions points to demand for an enhanced user experience. Digital estate planning combined with direct conversations with clients about this particularly weighty topic helps cement that relationship with the client and potentially with the other stakeholders in the next generation, especially if they, too, join the discussions.

Ultimately, it’s about the effectiveness of advisor-client communication, a significant currency that makes financial advisors more than order-takers in a digital world of cookie-cutter, low- or no-cost options. That’s not a recipe for long-term success.

“The legacy [estate-planning] conversation is emotional, often covering philanthropic and generational aspirations,” the Javelin report observes. It points to this empowering feature in our platform: “OneDigitalTrust, for example, creates a client area where notes can be appended to the system, allowing the client to memorialize and express those aspirations and sentiments for advisors, kids and other beneficiaries.”

Differentiation and Commoditization

That vital communication feature – among others – helps OneDigitalTrust continue to push out the leading edge of humanizing digital estate planning and, most critically, the ability for advisors to differentiate themselves in the uber-competitive fintech world.

OneDigitalTrust, as the Javelin report observes, is also out front with integrating personal financial data into its platforms. That gives financial services providers the ability to wade through multi-party, multi-platform morass to add even more value.

Financial services providers are keenly aware of the commoditization of their products and services and the need to differentiate. A robust foundation for that is personal service that uses digital products to help leverage meaningful conversations around the unique access financial planners have to their clients’ assets.

That conversation should include how to distribute those assets when the time comes without sending that part of the business elsewhere. “Advisors must consider expanding their business model by leveraging digital estate planning solutions,” the Javelin report concludes. “New channels of dialogue are opened with beneficiaries and family members who can become clients and advocate for the advisor’s expertise.”

And that helps the advisor and their employer build their value and legacy.

170M Americans need an estate plan. OneDigitalTrust offers a white-label, turnkey estate planning platform with pricing options tailored to the needs of individual credit unions and financial advisors.

Contact us today to learn more!