Announcing our SOC2 Type 2 Compliance.
Categories
Blog INSIGHTS

Healthcare vs. Financial Power of Attorney: Why Both Matter in Your Estate Plan

Not all critical roles in estate planning wait until death to take effect. Two key documents—the Healthcare Power of Attorney (sometimes called a Health Care Proxy or Advance Directive) and the Durable Financial Power of Attorney—let you appoint an agent to act on your behalf during your lifetime. While you are capable, you remain in control of your own decisions. If you become incapacitated, your chosen agent steps in to make healthcare or financial decisions as outlined in the document.

What is a Healthcare Power of Attorney?

A Healthcare Power of Attorney is a legal document that authorizes a chosen individual, called a Healthcare Agent (or Health Care Proxy in some states), to make medical decisions if a person is unable to do so themselves. These can include decisions about treatments, surgeries, and even life-sustaining measures like ventilation or feeding tubes. Many states also require that the document include HIPAA authorization so the Healthcare Agent can access medical records.

The COVID-19 pandemic brought renewed awareness to the importance of this document and the Healthcare Agent’s role. In scenarios where patients were sedated or placed on ventilators, decisions about care often fell to Healthcare Agents, highlighting the real-world impact of having this designation in place.

What is a Durable Financial Power of Attorney?

A Durable Financial Power of Attorney is a legal document that authorizes a chosen individual, called a Financial Agent or Attorney-in-Fact, to manage financial affairs immediately upon signing. Unlike a standard power of attorney, it remains valid even if the individual later becomes incapacitated. This could include:

  • Paying bills and managing accounts
  • Handling investments
  • Managing property
  • Working with tax professionals or attorneys on the individual’s behalf

This authority automatically ends at death, at which point the Executor (also called a Personal Representative) assumes control.

For an aging population, this document—and the Financial Agent appointed under it—are critical to protecting assets and preventing financial mismanagement or exploitation. Without formal authorization, even close family members might not have the legal ability to act, risking unpaid expenses or frozen accounts when it matters most.

Can One Person Serve Both Roles?

Often, yes. The same person can serve as both Healthcare Agent (appointed under a Healthcare Power of Attorney) and Financial Agent (appointed under a Durable Financial Power of Attorney). However, it’s important to assess whether the individual has the skills—and emotional capacity—to handle both responsibilities effectively. If separate individuals are appointed, it’s wise to ensure they can collaborate, especially since medical decisions often have financial implications.

Who May Not Be the Best Candidates for These Roles?

Not everyone is an ideal choice. For example:

  • Minors and convicted felons are often legally restricted from serving
  • A healthcare agent generally cannot be the operator of a facility currently providing treatment unless they are related to the patient by blood, marriage, or adoption
  • Someone with a history of financial mismanagement may not be the strongest candidate for a financial role

Why Thoughtful Planning is Key

Assigning these roles requires more than picking someone “close.” It requires trust, clarity, and consideration of each person’s qualifications. When these decisions are left unmade, families can face legal barriers, confusion, or conflicts during already difficult times.

OneDigitalTrust equips financial institutions, advisors, and banks with tools to help clients formally assign these roles, supported by educational resources and step-by-step guidance. With our platform, these essential roles aren’t just names on a document—they’re informed decisions that provide clarity when it matters most.
Categories
Blog INSIGHTS

Why Choosing the Right Executor Matters

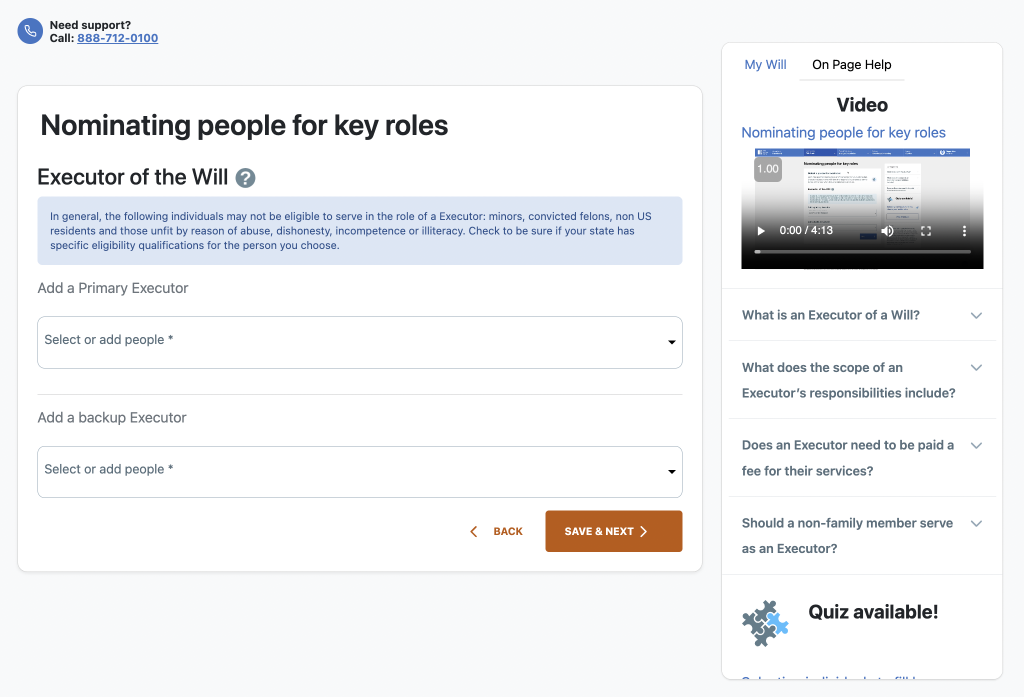
When creating an estate plan, much of the focus tends to be on “who gets what.” But just as critical is who makes it all happen. That’s the role of the Executor—the person (or institution) appointed in a Will to administer an estate after someone passes.

The choice of Executor carries significant weight. Not only are they responsible for carrying out the terms of the Will, but they must also navigate the probate process, settle debts, and manage relationships among heirs. For families, this can be a sensitive and emotional time, making the right Executor essential to minimizing conflict and ensuring a smooth settlement.

What Does an Executor Do?

The process usually starts when the nominated Executor files the Will and a petition for probate with the court. If approved, the court issues “letters testamentary” authorizing them to act.

Once officially appointed, an Executor’s duties typically include:

  • Notifying beneficiaries and potential heirs
  • Notifying known creditors and publishing notice to unknown creditors, as required by law
  • Collecting, inventorying, and valuing assets (courts often require a formal inventory and appraisal)
  • Paying outstanding debts, taxes, and final expenses (including obtaining an estate tax ID number and filing any required tax returns)
  • Managing and distributing assets according to the Will
  • Closing accounts and wrapping up the estate

Beyond paperwork, the Executor becomes the family’s point person—fielding questions, managing emotions, and keeping things on track. In families with existing conflicts, the right Executor can be the difference between a smooth process and ongoing disputes.

The role can also take months or even years, especially with complex estates or unique assets like businesses or property in multiple states (which may require ancillary probate in those jurisdictions). Beneficiaries may get impatient, so the Executor needs the time, patience, and commitment to see it through.

Who Should Serve as Executor?

While many people appoint a family member or close friend, it’s important to consider:

  • Financial savvy: Executors often handle complex financial tasks. Someone who struggles with finances may not be the ideal choice.
  • Location: If an Executor lives out of state, they may face logistical challenges depending on the jurisdiction. Some states require out-of-state Executors to appoint an in-state agent or post a bond, and a few restrict nonresidents unless they’re close relatives.
  • Family dynamics: Old rivalries or personal biases can make an otherwise well-intentioned choice problematic.

In some cases, families may choose to appoint a third-party or institutional Executor, such as a bank or trust company, particularly when estates are large or family dynamics are complex. All Executors—whether individual or institutional—must be appointed by the probate court, and corporate fiduciaries must also be authorized under state law. These entities typically charge a fee, which is often a percentage of the estate, and their appointment may require court approval depending on state laws.

A Critical but Often Overlooked Decision

Choosing an Executor isn’t just a formality. It’s a decision that shapes how an estate plan is executed in real life. And yet, it’s one of the most overlooked aspects of estate planning.

At OneDigitalTrust, our estate planning platform helps individuals name an Executor with guidance along the way. For financial institutions, wealth advisors, and credit unions, we can help provide their clients with the tools to prepare these critical decisions—helping ensure estates are settled promptly and with care.

Categories
Blog INSIGHTS

Rethinking Financial Education in a Digital World

Financial literacy is evolving. It’s no longer confined to in-person seminars, dense brochures, or scheduled advisor meetings. Today, consumers (especially Gen Z and Millennials) are learning in short bursts, through interactive content, on their own time. They turn to TikTok explainers for quick breakdowns, YouTube walkthroughs for how-to knowledge, and Reddit threads for shared experiences. They’re not waiting to be taught; they’re already learning.

This shift has transformed the role of financial tools. It’s not enough to simply offer functionality. To truly serve today’s consumers, platforms must teach while they guide, helping users understand what they’re doing and why it matters.

Estate planning is no exception.

Many individuals know it’s important, but don’t understand where to start. Or worse, they avoid it entirely because the process seems overwhelming. That’s why OneDigitalTrust was built not just as an estate planning platform, but as an educational experience that meets people where they are: online, curious, and ready to learn. 

How OneDigitalTrust Builds Financial Literacy Into Every Step

At OneDigitalTrust, we believe education should be woven directly into the planning experience. Users don’t need to pause or search elsewhere—they get the information they need in the moment, with in-context explanations and interactive support that reinforce understanding as they go.

Here’s how we make it happen:

1. On-Page Help Throughout the Planning Journey

Estate planning includes terms and decisions most people aren’t familiar with—like naming executors, understanding how to divide an estate, or knowing what a revocable trust really means.

Instead of sending users to a separate help center, OneDigitalTrust provides On-Page Help that’s integrated into the flow of the platform. When a user encounters a question—like how to handle unequal asset distribution or who should be appointed as power of attorney—clear explanations can be navigated to on the right side of the page.

This guidance is written in plain language, and includes expandable dropdowns to go deeper when users want more context.

2. Embedded Educational Videos to Support Decision-Making

In addition to written guidance, OneDigitalTrust includes short video tutorials placed directly within the estate plan creation process. These videos walk users through key topics—like nominating people for key roles—so they can understand both the task at hand and the bigger-picture implications.

It’s not just about getting the document done—it’s about making informed, confident decisions along the way.

3. Estate IQ Quizzes: Turning Knowledge Into Confidence

OneDigitalTrust also offers interactive Estate IQ quizzes to help reinforce key concepts. These short, scenario-based quizzes cover foundational topics like:

  • Key concepts on the distribution of assets
  • Understanding Probate
  • Key differences between a Last Will and a Living Trust

Each quiz is designed to take between 5-15 minutes and helps highlight areas where users can test their knowledge, as well as where they may want to learn more. Results contribute to a personalized Estate IQ score, giving users a sense of progress and confidence over time.

For Financial Institutions and Advisors, Education = Engagement

For credit unions, banks, and financial advisors, education isn’t just a value-add—it’s a trust builder. Consumers are more likely to engage with tools they understand, and more likely to stick with institutions that empower them to learn and grow.

By offering OneDigitalTrust as part of your client experience, you’re not just helping someone create a will. You’re helping them understand why it matters. That turns a transactional interaction into a meaningful, lasting relationship.

And because the platform includes built-in education, advisors don’t have to answer every question directly. The platform does the heavy lifting so conversations can go deeper, faster, and more confidently.

Learning as a Feature, Not a Barrier

Financial education doesn’t have to slow people down. When it’s embedded naturally—through on-page help, short videos, quick quizzes—it empowers people to take action with clarity.

Estate planning is one of the most important things a person can do for their future and their family. With OneDigitalTrust—branded or co-branded by their trusted financial institution or advisor—they don’t just get it done. They understand what they’re doing, and they’ll remember who helped them do it right.

Categories
Blog INSIGHTS

What Happens If You Die Without a Will—And How OneDigitalTrust Helps You Avoid It

Estate planning isn’t just for the ultra-wealthy—it’s for anyone who wants to ensure their wishes are known, and their family isn’t left guessing. But what happens when someone passes away without a will?

Dying without a will (known legally as “dying intestate”) means state law decides who inherits your assets. That often leads to confusion, delays, and outcomes that may be far from what you wanted.

When the Law Doesn’t See the Full Picture

Modern families are diverse. Many people live with long-term partners, raise children from previous relationships, or have close ties with friends and chosen family. But most inheritance laws still prioritize marriage and blood relation, often leaving important relationships unrecognized. Those closest to someone may end up with nothing.

People with fewer resources—especially in underserved communities—are also less likely to have wills. Barriers include cost, limited access to attorneys, procrastination, or thinking they don’t own enough to make it worthwhile. Yet even modest estates, like a car or savings account, can be difficult to manage without a plan.

Here are a few real-world scenarios that highlight just how complicated things can get when there’s no will in place:

The Unmarried Partner Left Behind

Lena and Greg had been together for over a decade. They shared a home, a dog, and joint finances—but weren’t legally married. When Greg passed unexpectedly, Lena assumed she’d be able to manage things. But because Greg didn’t leave a will, state law didn’t recognize their relationship. Greg’s estranged parents became the legal heirs, and Lena had no legal claim to their shared home.

This situation is becoming more common as more Americans cohabitate without marrying. Yet inheritance law hasn’t evolved to reflect that shift. 

With OneDigitalTrust, users can include non-family members in their estate plan. Friends, partners, and advisors can be added, edited, or removed at any time. You can nominate them as beneficiaries for specific assets or assign them to key roles like Executor, Guardian, or Power of Attorney—ensuring your plan reflects your real-life relationships, not just legal defaults.

The “Too Soon” Assumption

Jason, 35, was healthy, single, and working hard to build a more stable future. Like many people in his position, he figured estate planning could wait—something for when he had more time, more money, or more to leave behind. Like many people, he didn’t enjoy thinking about death—it felt morbid, premature, and easy to avoid. But after a sudden accident, his family faced legal hurdles just to access his accounts or make medical decisions. 

People with fewer resources often delay planning, believing they don’t need it or can’t afford it. Whether choosing a basic or custom will, OneDigitalTrust makes getting started easy, guided, and affordable. Users can create a legally valid plan in minutes—no lawyer needed—ensuring their real wishes are protected before it is too late.

The Guardianship Gap

Ana was a single mother raising two minor children. She always meant to put a plan in place—but between work, childcare, and life’s daily demands, it stayed on the back burner. When a car accident took her life, her extended family was left with no clear direction. Disagreements quickly arose: one relative lived nearby and offered stability, another insisted Ana had “mentioned” different wishes years ago. 

Without written instructions, guardianship decisions often land in court, even when family members have good intentions. That can lead to stress, conflict, and outcomes that don’t reflect what the parent would have wanted.

With OneDigitalTrust, users can formally designate a legal guardian for their minor children in minutes—right within the will creation flow. They can also add a backup guardian, update their choices at any time, and read on-page help with additional information such as appointing a guardian who lives out of state.

The Common Thread: No One Planned to Leave a Mess

Even the most loving, organized people rarely expect their lives to end without warning. But without a will, the law steps in—and too often, it doesn’t reflect how people actually live, love, and build families today. 

That’s why creating an estate plan is one of the most important steps you can take. OneDigitalTrust helps bridge that gap with tools that make estate planning accessible, customizable, and aligned with real life. Because protecting what matters shouldn’t depend on assumptions.

Categories
Blog INSIGHTS

Spring Cleaning for Estate Plans: How Financial Institutions and Advisors Can Help Clients Stay Prepared

Spring is a season of renewal—a perfect time for financial institutions and advisors to help clients and members refresh their estate plans. Just as people declutter their homes, reviewing wills, beneficiaries, and power of attorney designations ensures financial plans stay current and aligned with life changes. With digital tools like the OneDigitalTrust platform, updating an estate plan is now easier and more accessible than ever.

How Financial Institutions Can Drive Estate Plan Updates

Financial institutions play a key role in keeping customers financially secure, yet estate planning often falls by the wayside. Many people create a will once and forget to update it after major life events like marriage, divorce, or having children. A well-placed digital reminder—through online banking platforms, mobile app notifications, or email campaigns—can nudge customers to review their plans before issues arise.

With the OneDigitalTrust platform, financial institutions can offer estate planning as part of their digital banking experience. Instead of requiring clients to visit an attorney’s office or navigate complex paperwork, they can create, update, and store their estate plans online. By integrating the OneDigitalTrust platform into their offerings, banks and credit unions enhance customer engagement while reinforcing their role as trusted financial partners.

How Financial Advisors Can Guide Clients Through Estate Plan Reviews

For financial advisors, estate planning checkups should be a routine part of client reviews. Estate plans directly impact wealth transfer, tax strategies, and asset protection—yet clients often overlook them. A quick review of beneficiary designations, power of attorney documents, and asset distribution strategies can prevent probate issues and ensure clients’ wishes are carried out.

The OneDigitalTrust suite of estate planning tools makes it simple for advisors to incorporate estate planning into financial reviews. Instead of referring clients elsewhere, advisors can provide an easy-to-use digital platform that allows clients to update their documents in real-time. This strengthens the advisor-client relationship and ensures estate planning stays integrated with broader financial goals.

A Simple Solution That Strengthens Client Relationships

Estate planning doesn’t have to be complicated or time-consuming. By incorporating the OneDigitalTrust suite, financial institutions and advisors can make estate plan updates seamless, accessible, and routine. A simple spring cleaning check-in can save clients from future legal headaches, ensuring their financial and personal wishes are always up to date.

Now is the perfect time to start the conversation—before outdated plans become real problems. Want to see how OneDigitalTrust can help? Contact us to learn more.

Categories
Blog INSIGHTS

Anticipating the Future: How Financial Institutions Can Stay Ahead in Estate Planning

The financial services landscape is evolving at an unprecedented pace, and institutions that wait for change to happen before adapting risk falling behind. As pointed out in the article “Meeting the future before it arrives,” the key to long-term success is anticipating the future—rather than reacting to it.

For credit unions, banks, and financial advisory firms, estate planning represents one of those critical areas where proactive innovation can set institutions apart. While many financial institutions focus on wealth accumulation, far fewer take an active role in helping clients protect and transfer that wealth efficiently. That’s where digital estate planning solutions come in.

Anticipating the Future of Estate Planning

Historically, estate planning has been an attorney-driven, paper-heavy process—often delayed or overlooked by clients. But today, technology is redefining expectations. Digital-first solutions are making estate planning more accessible, affordable, and integrated into the broader financial services ecosystem.

Forward-thinking financial institutions are recognizing that:

  • Clients expect seamless, digital experiences in financial planning.
  •  Estate planning is a key differentiator in holistic wealth management.
  •  Proactive engagement deepens relationships and strengthens client loyalty.
Why Estate Planning Can’t Wait

Waiting until clients request estate planning solutions is like waiting until retirement to start saving—it’s too late to maximize the benefits. Financial institutions must proactively provide tools and guidance, ensuring clients don’t put off estate planning until a crisis forces them to act.

How Financial Institutions Can Stay Ahead

Integrate Estate Planning into Digital Banking & Wealth Management
Clients should have easy access to estate planning tools within their digital banking platforms—just as they do with budgeting, investing, and insurance. Institutions that provide an embedded estate planning experience will build trust and engagement.

Leverage Technology to Simplify the Process
Modern estate planning platforms, like the OneDigitalTrust platform, offer an intuitive, step-by-step process that allows clients to create wills, trusts, and beneficiary designations online. These solutions ensure clients can plan proactively without the friction of traditional legal processes.

Use Estate Planning as a Relationship-Building Tool
By offering estate planning solutions, financial institutions can:

  • Position themselves as trusted, long-term partners in financial wellness.
  • Strengthen engagement with millennial and Gen X clients, who increasingly seek digital solutions.
  • Deepen relationships with multi-generational clients by helping families prepare for wealth transfer.

Future-Proofing Your Institution Starts Now

Credit unions and banks that embrace estate planning technology today will be the ones leading the industry tomorrow. Rather than reacting to disruption, they’ll be shaping the future of financial services—ensuring they remain relevant, competitive, and indispensable to their clients.

Are You Ready to Meet the Future Before It Arrives?

Let’s talk about how your institution can integrate digital estate planning into your client experience and stay ahead of the curve. Reach out to learn more.


Categories
Blog INSIGHTS

Empathy in Estate Planning: How Financial Advisors Can Guide Clients to Peace of Mind

Estate planning is an essential part of financial management, yet many individuals delay or avoid it due to several common challenges. These challenges often stem from practical concerns rather than just emotional hesitation. Financial advisors play a critical role in helping clients navigate these obstacles and make informed decisions. With digital tools like the OneDigitalTrust financial advisor portal, advisors can streamline the estate planning process and provide valuable resources to address these challenges effectively.

Key Challenges in Estate Planning

  1. Avoidance of Mortality Discussions
    Estate planning requires individuals to consider what will happen after they pass away, a topic that many prefer to avoid. As mentioned in an interview with OneDigitalTrust’s CEO Sonny Kapoor, “Humans have an instinctive and ongoing existential fear of death. This ‘death anxiety’ can create cognitive distortion, which makes people act irrationally, such as putting off essential estate planning.” Using the OneDigitalTrust financial advisor portal, advisors can provide step-by-step guidance, making the process less daunting and more structured for clients.

  2. Complex Family Dynamics
    Estate planning frequently highlights complex family situations, such as blended families, sibling disputes, or strained relationships. These complexities can make decision-making difficult and delay the process.

  3. Concerns About Control and Management
    Clients may worry about losing control over their assets or doubt the ability of their beneficiaries to manage the inheritance wisely. This concern can result in hesitation or indecision during the planning process.

Strategies for Financial Advisors Using Estate Planning Platforms

  1. Building Trust and Rapport
    Establishing a strong, trusting relationship is fundamental. Clients are more likely to open up about their fears and concerns when they feel their advisor genuinely cares and understands their situation. A financial advisor portal, like OneDigitalTrust, enables advisors to see what their clients have entered in their estate plan, allowing them to offer timely assistance and maintain consistent communication, which fosters trust and transparency throughout the process.

  2. Educating and Empowering
    Educate clients about the estate planning process and the options available to them. Empowering clients with knowledge can reduce anxiety and help them feel more in control of their decisions.

  3. Facilitating Family Discussions
    Offer to mediate or facilitate family meetings to discuss estate plans. Having a neutral third party present can help diffuse tensions and ensure that everyone’s voice is heard. The portal can give insights on the family circumstances, making it easier for financial advisors to initiate these conversations. The OneDigitalTrust financial advisor portal’s detailed insights into the client’s estate plan help advisors prepare for these discussions, while alerts on specific plan details ensure advisors are ready to address possible sensitive topics.

  4. Providing Resources
    Recommend resources such as grief counseling, support groups, or literature on coping with loss and planning for the future. These resources can help clients process their emotions outside the advisory context.

  5. Tailoring the Approach
    Recognize that each client is unique and may require a different approach. Some clients may prefer a more direct and factual conversation, while others may need a gentler, more supportive dialogue. The portal’s just-in-time alerts about important plan details, allow advisors to adapt their approach, ensuring a personalized experience that aligns with each client’s specific needs and circumstances.


Estate planning is inherently emotional, but with thoughtful, empathetic support from financial advisors, clients can navigate these complexities more comfortably. By understanding the psychological challenges and employing strategies to support clients, financial advisors can enhance their relationships with clients and help them create estate plans that reflect their values and wishes. Leveraging estate planning platforms like the OneDigitalTrust platform, with a robust financial advisor portal, further empowers advisors to provide comprehensive, empathetic support, fostering trust, reducing anxiety, and enabling clients to make informed decisions that bring peace of mind.


Categories
Blog INSIGHTS

The High Cost of Doing Nothing: Why Financial Institutions Should Promote Estate Planning

Estate planning is a critical service that helps individuals secure their financial futures and protect generational wealth. Yet, many customers and members of financial institutions delay the process, often perceiving it as too complicated or costly. For financial institutions and advisors, the opportunity lies in addressing this gap by offering tools and resources that simplify estate planning. Even straightforward solutions can make a substantial difference in protecting families and ensuring financial security, highlighting the value institutions and advisors can provide to their communities and clients.

Why Having an Estate Plan Matters

The biggest oversight for many individuals is not having any estate plan at all. For financial institutions, this presents an opportunity to educate and support customers in avoiding this common mistake. As Barbara Ginty, a Certified Financial Planner and host of the Future Rich Podcast, explains:

“The biggest mistake is not having an estate plan. If you want to create generational wealth, you need a comprehensive estate plan.”

Without any plan in place, customers and members may leave their families to navigate unnecessary delays, expenses, and emotional stress. By providing resources and tools, financial institutions can help their clients avoid these challenges, whether through simple solutions or more comprehensive plans. Even for customers and members with straightforward needs, the reassurance that their affairs are in order is a significant value-add that institutions can offer.

Tackling the Cost Barrier

Cost is often cited as a major reason people delay estate planning. Financial institutions are in a unique position to address this concern by offering accessible and affordable tools to their customers, like OneDigitalTrust. Traditional estate planning services can be expensive, but solutions like OneDigitalTrust provide a cost-effective and efficient alternative for creating legally valid plans.

For individuals with straightforward needs, these platforms offer essential tools to create wills, trusts, and other key documents. By partnering with such solutions, financial institutions can help their clients overcome the cost barrier, ensuring that protection and planning are within reach for all. Providing these resources demonstrates a commitment to financial well-being and removes a significant obstacle to getting started.

Staying Organized is Key

Organizational challenges are a common hurdle in estate planning. Financial institutions and financial advisors can play a crucial role in helping their clients navigate this process by promoting the importance of keeping financial records in order. As Patty Fitzsimmons, vice president of accounting at Aquilance, points out:

“Not creating or maintaining a solid accounting and record-keeping system by a family is one of the biggest mistakes in the estate planning process.”

Encouraging clients to maintain a clear understanding of their financial situation—assets, debts, and overall net worth—is foundational to effective planning. Estate planning platforms can complement this effort, but they work best when paired with accurate and up-to-date financial information. By supporting clients in creating asset inventories or net worth statements, financial institutions and advisors can help streamline the planning process and minimize potential confusion down the road.

Fitzsimmons adds:
“Making assumptions about the current state of a family’s situation is another big mistake we see. It is particularly important that the current reality is clearly understood.”

Through education and accessible tools, institutions and advisors can empower their members and clients to build a solid foundation for estate planning.

The Bottom Line: Start Small, But Start

Estate planning may seem daunting, especially for those just beginning the process. However, waiting for the perfect moment or for the ability to afford expensive professionals can be a risky approach. Financial institutions can help their clients take the first step by emphasizing that a simple, foundational plan is better than no plan at all.

A straightforward estate plan, while basic, can offer significant protection and peace of mind. As clients’ needs evolve, estate planning can become more complex, but starting with a solid foundation, such as the one offered through OneDigitalTrust, can provide a critical safety net from the start. Financial institutions can play a key role in helping their clients navigate this journey without the burden of high costs or complexity.

In the end, estate planning doesn’t need to be overwhelming. Encouraging clients to take small steps now, using accessible tools, can ensure they have a plan in place that safeguards their financial future and offers clarity for their loved ones.

Categories
Blog INSIGHTS

Around the Thanksgiving Table: How Financial Advisors Can Help Clients Start the Estate Planning Conversation

As Thanksgiving approaches, families gather together to reflect, share memories, and appreciate one another. While the holiday is often focused on gratitude, it also presents a unique opportunity to introduce important conversations, like estate planning. For financial advisors working with clients and their families, this time of year can offer an ideal moment to guide clients toward having these crucial discussions with loved ones. Here’s how to approach estate planning in a way that fosters understanding, openness, and long-term planning.

Create a Comfortable Setting for Conversations

The Thanksgiving holiday provides a natural, relaxed environment for estate planning discussions. Financial advisors can help clients understand how to bring up the topic gently, perhaps during quieter moments when families are engaged in sharing memories. By emphasizing that it’s about preparing for the future rather than focusing on the daunting aspects of death, clients can initiate conversations that feel natural and empowering rather than uncomfortable or rushed.

Position Estate Planning as a Family Benefit

Rather than framing estate planning as a task, encourage clients to highlight its value as a tool for peace of mind and family unity. By planning ahead, families can ensure that assets are distributed according to their wishes and that loved ones are cared for. For financial advisors, helping clients position estate planning in this light can turn what may seem like an intimidating subject into one that feels proactive, supportive, and considerate of family members’ needs.

Foster a Sense of Togetherness in Planning

Estate planning is more than legal documents—it’s about preserving family legacies and strengthening connections. Financial advisors can guide clients in thinking about how their estate plan will protect both their financial assets and the family bonds they’ve worked to nurture. By encouraging clients to view the process as a shared family goal, financial advisors can make estate planning feel like a collaborative endeavor that benefits everyone involved.

Lead with Empathy and Understanding

Acknowledge that estate planning can stir up complex emotions. Each family member may have different feelings about aging, legacy, and wealth distribution. Financial advisors can assist their clients in leading these discussions with empathy, ensuring all voices are heard and respected. This approach will foster an atmosphere of mutual understanding, making the conversation about estate planning less intimidating and more about ensuring that everyone feels comfortable and valued.

Use Personal Stories to Encourage Reflection

Thanksgiving is a time of reflection, which provides an opportunity for financial advisors to encourage clients to share personal stories about their family’s legacy and what they hope to pass down. By sharing stories of personal experiences, clients can see estate planning as a continuation of their family narrative, making the conversation more relatable and heartfelt.

Keep the Dialogue Open and Ongoing

While Thanksgiving may be the perfect opportunity to start the conversation, estate planning is an ongoing process. Encourage clients to view this as just the beginning of a broader conversation with their families, one that can continue beyond the holiday season. Financial advisors can position themselves as a long-term partner in these conversations, offering guidance and tools to help clients revisit and refine their plans as circumstances change.

Conclusion

By guiding clients to approach estate planning conversations with their families during Thanksgiving, financial advisors can help their clients prepare for the future with a sense of peace and purpose. The goal isn’t to rush the process but to initiate an ongoing dialogue that ensures that family legacies are protected, and the right decisions are made for future generations. With the right approach, estate planning can be a meaningful and empowering conversation, benefiting both families and the advisors that help them navigate these important decisions.

Categories
Blog INSIGHTS

Avoid These Real-Life Horror Stories: The Importance of Estate Planning for Your Members, Customers and Employees This Halloween

As Halloween approaches, financial advisors and institutions must prepare for more than just haunted houses and spooky tales. The true horror your clients may face is the financial chaos left behind without a proper estate plan. Unfortunately, when clients neglect their estate planning, their loved ones are often left with legal battles, unnecessary taxes, and emotional strain. Let’s look at some real-life cases of estate planning gone wrong and how you, as financial advisors and institutions, can protect your clients from becoming part of their own financial horror stories.

The Case of the Missing Will: A Family Conflict You Can Help Prevent

After the sudden passing of a client, two adult children found themselves in a nightmare scenario—no will had been created. The mother, assuming her intentions were clear, had left no formal documentation of her wishes. This led to a prolonged legal battle, as both siblings fought for what they believed was their rightful inheritance. With no will to guide the process, the courts took over, costing the family tens of thousands of dollars in legal fees. By the time the estate was settled, the family’s wealth had been significantly diminished, and the siblings’ relationship was irreparably damaged.

How Financial Advisors Can Help

This situation could have been entirely avoided with your intervention. Regularly discussing estate planning with clients and encouraging them to create or update their wills can prevent this kind of familial conflict. As a financial advisor, you have the unique opportunity to ensure your clients’ wishes are documented clearly and their loved ones are spared from drawn-out court battles. By incorporating estate planning services into your practice, you can add significant value to your client relationships.

The Phantom Heirs: An Outdated Will That Left Heirs Empty-Handed

A middle-aged client unexpectedly passed away, leaving behind two adult children. Both assumed they would inherit their father’s estate. However, when his will was located, it was revealed that it hadn’t been updated in 20 years—before his divorce. The outdated will left everything to his ex-wife, leaving his children with nothing. To make matters worse, he had neglected to update the beneficiaries on his life insurance policy, so his ex-wife also received the full payout.

How Financial Institutions Can Help

Regularly reviewing and updating estate plans is crucial, particularly after major life events such as divorce or the birth of children. As part of your financial services, offering estate plan reviews at key life milestones can protect your clients from this type of oversight. By providing access to estate planning platforms like OneDigitalTrust, your institution can help clients stay up to date and avoid unintended outcomes like these.

The Tax Nightmare: A Family Forced to Sell Assets Due to Poor Planning

In another unfortunate case, a family was devastated to discover the massive estate tax liability they faced after the death of their patriarch, a successful business owner. Although they were expecting to inherit a large estate, they hadn’t anticipated the substantial tax bill. To cover it, they were forced to sell off cherished family assets, including a vacation home that had been in the family for generations.

How Financial Advisors Can Help

This scenario could have been mitigated with proactive tax planning as part of a broader estate strategy. Financial advisors are in the ideal position to help clients structure their estates in ways that minimize tax burdens. By implementing tax-efficient strategies—such as creating trusts or incorporating charitable giving—you can help clients preserve their wealth for future generations. Encouraging clients to integrate estate planning with their overall financial strategy ensures they avoid such costly mistakes.

Helping Your Clients Escape the Horror: Simplifying Estate Planning

Estate planning can be a daunting task for clients, and many delay it until it’s too late. However, as financial institutions and advisors, you can make the process easier for your clients by offering access to streamlined estate planning solutions.

OneDigitalTrust is designed to simplify the process, enabling your clients to create or update their wills, set up trusts, and manage their estate plans with ease. By integrating this platform into your services, you provide clients with a comprehensive tool that helps them protect their assets and ensure their wishes are fulfilled.

This Halloween, help your clients and members avoid real-life financial horror stories by guiding them toward effective estate planning. With OneDigitalTrust, you can offer them peace of mind while strengthening your role as a trusted advisor or financial institution.