Announcing our SOC2 Type 2 Compliance.
Categories
Blog INSIGHTS

Healthcare vs. Financial Power of Attorney: Why Both Matter in Your Estate Plan

Not all critical roles in estate planning wait until death to take effect. Two key documents—the Healthcare Power of Attorney (sometimes called a Health Care Proxy or Advance Directive) and the Durable Financial Power of Attorney—let you appoint an agent to act on your behalf during your lifetime. While you are capable, you remain in control of your own decisions. If you become incapacitated, your chosen agent steps in to make healthcare or financial decisions as outlined in the document.

What is a Healthcare Power of Attorney?

A Healthcare Power of Attorney is a legal document that authorizes a chosen individual, called a Healthcare Agent (or Health Care Proxy in some states), to make medical decisions if a person is unable to do so themselves. These can include decisions about treatments, surgeries, and even life-sustaining measures like ventilation or feeding tubes. Many states also require that the document include HIPAA authorization so the Healthcare Agent can access medical records.

The COVID-19 pandemic brought renewed awareness to the importance of this document and the Healthcare Agent’s role. In scenarios where patients were sedated or placed on ventilators, decisions about care often fell to Healthcare Agents, highlighting the real-world impact of having this designation in place.

What is a Durable Financial Power of Attorney?

A Durable Financial Power of Attorney is a legal document that authorizes a chosen individual, called a Financial Agent or Attorney-in-Fact, to manage financial affairs immediately upon signing. Unlike a standard power of attorney, it remains valid even if the individual later becomes incapacitated. This could include:

  • Paying bills and managing accounts
  • Handling investments
  • Managing property
  • Working with tax professionals or attorneys on the individual’s behalf

This authority automatically ends at death, at which point the Executor (also called a Personal Representative) assumes control.

For an aging population, this document—and the Financial Agent appointed under it—are critical to protecting assets and preventing financial mismanagement or exploitation. Without formal authorization, even close family members might not have the legal ability to act, risking unpaid expenses or frozen accounts when it matters most.

Can One Person Serve Both Roles?

Often, yes. The same person can serve as both Healthcare Agent (appointed under a Healthcare Power of Attorney) and Financial Agent (appointed under a Durable Financial Power of Attorney). However, it’s important to assess whether the individual has the skills—and emotional capacity—to handle both responsibilities effectively. If separate individuals are appointed, it’s wise to ensure they can collaborate, especially since medical decisions often have financial implications.

Who May Not Be the Best Candidates for These Roles?

Not everyone is an ideal choice. For example:

  • Minors and convicted felons are often legally restricted from serving
  • A healthcare agent generally cannot be the operator of a facility currently providing treatment unless they are related to the patient by blood, marriage, or adoption
  • Someone with a history of financial mismanagement may not be the strongest candidate for a financial role

Why Thoughtful Planning is Key

Assigning these roles requires more than picking someone “close.” It requires trust, clarity, and consideration of each person’s qualifications. When these decisions are left unmade, families can face legal barriers, confusion, or conflicts during already difficult times.

OneDigitalTrust equips financial institutions, advisors, and banks with tools to help clients formally assign these roles, supported by educational resources and step-by-step guidance. With our platform, these essential roles aren’t just names on a document—they’re informed decisions that provide clarity when it matters most.
Categories
Blog INSIGHTS

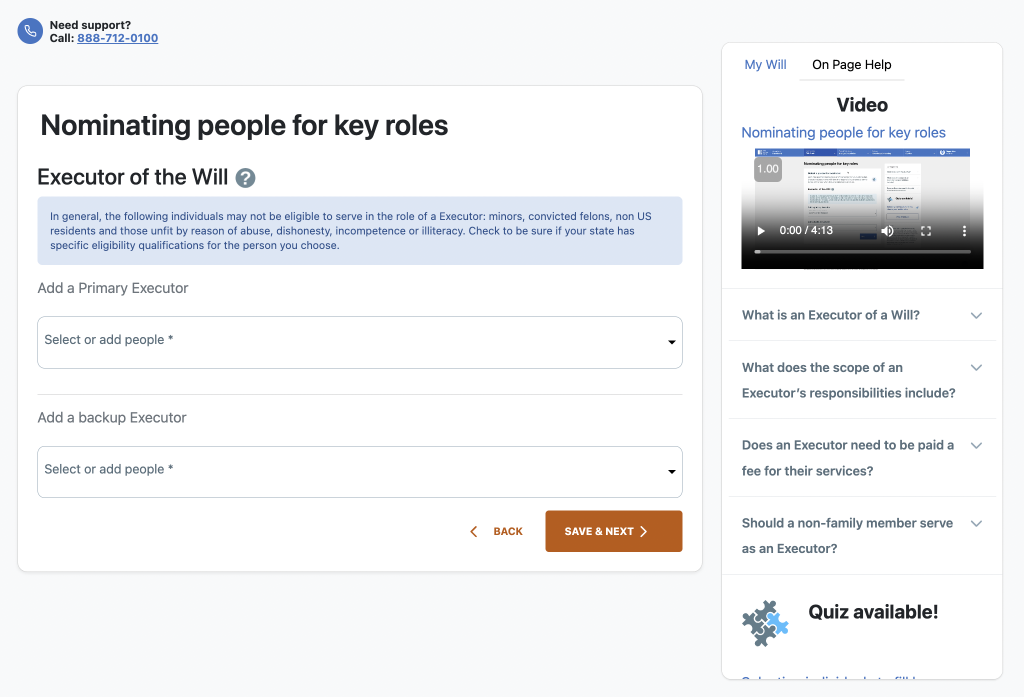
Why Choosing the Right Executor Matters

When creating an estate plan, much of the focus tends to be on “who gets what.” But just as critical is who makes it all happen. That’s the role of the Executor—the person (or institution) appointed in a Will to administer an estate after someone passes.

The choice of Executor carries significant weight. Not only are they responsible for carrying out the terms of the Will, but they must also navigate the probate process, settle debts, and manage relationships among heirs. For families, this can be a sensitive and emotional time, making the right Executor essential to minimizing conflict and ensuring a smooth settlement.

What Does an Executor Do?

The process usually starts when the nominated Executor files the Will and a petition for probate with the court. If approved, the court issues “letters testamentary” authorizing them to act.

Once officially appointed, an Executor’s duties typically include:

  • Notifying beneficiaries and potential heirs
  • Notifying known creditors and publishing notice to unknown creditors, as required by law
  • Collecting, inventorying, and valuing assets (courts often require a formal inventory and appraisal)
  • Paying outstanding debts, taxes, and final expenses (including obtaining an estate tax ID number and filing any required tax returns)
  • Managing and distributing assets according to the Will
  • Closing accounts and wrapping up the estate

Beyond paperwork, the Executor becomes the family’s point person—fielding questions, managing emotions, and keeping things on track. In families with existing conflicts, the right Executor can be the difference between a smooth process and ongoing disputes.

The role can also take months or even years, especially with complex estates or unique assets like businesses or property in multiple states (which may require ancillary probate in those jurisdictions). Beneficiaries may get impatient, so the Executor needs the time, patience, and commitment to see it through.

Who Should Serve as Executor?

While many people appoint a family member or close friend, it’s important to consider:

  • Financial savvy: Executors often handle complex financial tasks. Someone who struggles with finances may not be the ideal choice.
  • Location: If an Executor lives out of state, they may face logistical challenges depending on the jurisdiction. Some states require out-of-state Executors to appoint an in-state agent or post a bond, and a few restrict nonresidents unless they’re close relatives.
  • Family dynamics: Old rivalries or personal biases can make an otherwise well-intentioned choice problematic.

In some cases, families may choose to appoint a third-party or institutional Executor, such as a bank or trust company, particularly when estates are large or family dynamics are complex. All Executors—whether individual or institutional—must be appointed by the probate court, and corporate fiduciaries must also be authorized under state law. These entities typically charge a fee, which is often a percentage of the estate, and their appointment may require court approval depending on state laws.

A Critical but Often Overlooked Decision

Choosing an Executor isn’t just a formality. It’s a decision that shapes how an estate plan is executed in real life. And yet, it’s one of the most overlooked aspects of estate planning.

At OneDigitalTrust, our estate planning platform helps individuals name an Executor with guidance along the way. For financial institutions, wealth advisors, and credit unions, we can help provide their clients with the tools to prepare these critical decisions—helping ensure estates are settled promptly and with care.

Categories
Blog INSIGHTS

Rethinking Financial Education in a Digital World

Financial literacy is evolving. It’s no longer confined to in-person seminars, dense brochures, or scheduled advisor meetings. Today, consumers (especially Gen Z and Millennials) are learning in short bursts, through interactive content, on their own time. They turn to TikTok explainers for quick breakdowns, YouTube walkthroughs for how-to knowledge, and Reddit threads for shared experiences. They’re not waiting to be taught; they’re already learning.

This shift has transformed the role of financial tools. It’s not enough to simply offer functionality. To truly serve today’s consumers, platforms must teach while they guide, helping users understand what they’re doing and why it matters.

Estate planning is no exception.

Many individuals know it’s important, but don’t understand where to start. Or worse, they avoid it entirely because the process seems overwhelming. That’s why OneDigitalTrust was built not just as an estate planning platform, but as an educational experience that meets people where they are: online, curious, and ready to learn. 

How OneDigitalTrust Builds Financial Literacy Into Every Step

At OneDigitalTrust, we believe education should be woven directly into the planning experience. Users don’t need to pause or search elsewhere—they get the information they need in the moment, with in-context explanations and interactive support that reinforce understanding as they go.

Here’s how we make it happen:

1. On-Page Help Throughout the Planning Journey

Estate planning includes terms and decisions most people aren’t familiar with—like naming executors, understanding how to divide an estate, or knowing what a revocable trust really means.

Instead of sending users to a separate help center, OneDigitalTrust provides On-Page Help that’s integrated into the flow of the platform. When a user encounters a question—like how to handle unequal asset distribution or who should be appointed as power of attorney—clear explanations can be navigated to on the right side of the page.

This guidance is written in plain language, and includes expandable dropdowns to go deeper when users want more context.

2. Embedded Educational Videos to Support Decision-Making

In addition to written guidance, OneDigitalTrust includes short video tutorials placed directly within the estate plan creation process. These videos walk users through key topics—like nominating people for key roles—so they can understand both the task at hand and the bigger-picture implications.

It’s not just about getting the document done—it’s about making informed, confident decisions along the way.

3. Estate IQ Quizzes: Turning Knowledge Into Confidence

OneDigitalTrust also offers interactive Estate IQ quizzes to help reinforce key concepts. These short, scenario-based quizzes cover foundational topics like:

  • Key concepts on the distribution of assets
  • Understanding Probate
  • Key differences between a Last Will and a Living Trust

Each quiz is designed to take between 5-15 minutes and helps highlight areas where users can test their knowledge, as well as where they may want to learn more. Results contribute to a personalized Estate IQ score, giving users a sense of progress and confidence over time.

For Financial Institutions and Advisors, Education = Engagement

For credit unions, banks, and financial advisors, education isn’t just a value-add—it’s a trust builder. Consumers are more likely to engage with tools they understand, and more likely to stick with institutions that empower them to learn and grow.

By offering OneDigitalTrust as part of your client experience, you’re not just helping someone create a will. You’re helping them understand why it matters. That turns a transactional interaction into a meaningful, lasting relationship.

And because the platform includes built-in education, advisors don’t have to answer every question directly. The platform does the heavy lifting so conversations can go deeper, faster, and more confidently.

Learning as a Feature, Not a Barrier

Financial education doesn’t have to slow people down. When it’s embedded naturally—through on-page help, short videos, quick quizzes—it empowers people to take action with clarity.

Estate planning is one of the most important things a person can do for their future and their family. With OneDigitalTrust—branded or co-branded by their trusted financial institution or advisor—they don’t just get it done. They understand what they’re doing, and they’ll remember who helped them do it right.

Categories
Blog INSIGHTS

Mourning Has Multidimensional Costs – How Effective Estate Planning Can Ease Some of the Stress

Effective estate planning is crucial to the people your bank, credit union, financial advisory or other financial services company serves, whether they have come completely to grips with that reality or not. Having the right plans in place helps reduce the burden that loved ones bear in settling an estate and can significantly reduce the painful wait for it to settle.

The grief that mourners are left dealing with only makes the burden heavier. The costs can add up, and they involve more than just money. For instance, a study by the University of Georgia’s College of Public Health found that people in that state were 1.5 times more likely to visit a doctor 20 or more times in the two-year period after the death of a loved one. Even more striking, those over age 50 were more than twice as likely to die during bereavement.

The researchers cited depression and stress from the bereavement itself – the effects of which can include reverting to bad habits such as smoking, drinking and ignoring medical conditions. All that can add up to missed work, adding to the physical and material costs associated with the bereaved’s own health and paying the bills the deceased left behind.

Working-Aged People Bear the Burden

Wherever they live, the psychological and physical burden is most keenly felt by working-age people, those most likely to be part of the sandwich generation – responsible for caring for children and parents alike.

Employers can help. While there’s no federal bereavement leave policy, some states have them, and so do about 90% of U.S. companies, according to the International Foundation of Employee Benefit Plans.

But that time off is very limited, and one of the potentially biggest stresses, dealing with the liabilities and assets of the deceased’s estate can take months, not just a few days following a funeral. That time and uncertainty just add to the stress that, as we alluded to above, can take years off a person’s life.

That’s also one area where you can really step up as a holistic provider of financial services. A great first step is to offer streamlined, digital online estate planning platforms that are easy to use, simple but powerful, and complete. OneDigitalTrust is just that, as featured in new Javelin research. We provide single sign-on access to create legally valid wills, trusts, power of attorney, healthcare directives, guardianships, probate trackers and more, even a pet trust. It’s not just legal documents but we also offer estate analysis and optimization tools, plus hyper-personalized info to understand the implications of key aspects of the plan. These are all features that democratize capabilities previously available to the ultra-rich only. And, we provide a virtual vault for organizing all this, along with strategic guidance throughout your journey.

Cross-sell Effective Estate Planning Across Generations

Banks, credit unions, financial advisors, insurance agencies, benefits providers, and more can offer an easy-to-understand, effective estate planning process to help your organization attract and retain customers and members. Banks and credit unions that also have in-house advisors and insurers can use our platform as an opportunity to upsell your other services. That creates the opportunity for fee income while engaging with the consumers you serve in a highly valuable, personal and meaningful way. Our powerful platform also provides your organization with rich financial data on your members and customers so you can understand and better serve them. That’s a powerful cross-sell for you and a small cost many an aging baby boomer, Gen Xer, and even younger generations might happily bear when presented with the opportunity.

170M Americans need an estate plan. OneDigitalTrust offers a white-label, turnkey estate planning platform with pricing options tailored to the needs of banks, credit unions, financial advisors, wealth managers, insurance firms, employee benefit providers and more.

Contact us today to learn more!

Categories
Blog

Credit Unions Have Education and Opportunity Around Estate Planning

Death and taxes are two of life’s inevitabilities for credit union members and everybody else. But being prepared is optional, and that means opportunity for member-owned financial cooperatives to help make a difference when it comes to members’ estate planning.

A recent survey of more than 2,400 American adults conducted by YouGov for Caring.com found that only 34% had estate documents in place. The same survey found that people ages 18 to 34 are now 63% more likely to have an estate plan than they were in 2020. That points to growing interest from a sweet spot for growing engagement: the younger set.

As not-for-profit financial institutions whose core principles focus on financial wellness and opportunity, credit unions can build business and deepen relationships with all generations by including estate planning in your lineup of products and services.

Where there’s a will, there’s a way. Even if it’s a trust.

Wills and trusts have the same goal – distribution of the deceased’s assets (investments, savings, property and possessions) per their wishes legally and efficiently. But there are some key differences to note.

A will is a legal document that names an executor to oversee the liquidation of the estate and lays out how to distribute the assets among family, friends, charitable causes, etc., as well as such matters as naming a guardian for minor children.

Further, a will only takes effect after death, and in most cases a probate court must validate the document before the assets can be distributed. This can be a very lengthy and stressful process for your members if they have not planned properly.

Trusts, meanwhile, are also legal estate plans but with some significant differences. For one, people can serve as their own trustees while they are still live. That’s often the case with what’s probably the most common type of trust: living, or revocable, trusts. They are what they sound like: You can revoke and alter them to reflect your changing wishes and feelings as time goes on and circumstances change.

You also can use the assets placed into the living trust any way you want while you’re still alive and in charge, as well as name in advance who manages your financial affairs if you become incapacitated before death.

A will is typically simpler and less expensive than a trust, but the latter can provide faster distribution of assets and greater privacy. Trusts don’t go through probate. Probated documents, including wills, are typically public information.

Education and opportunity for your credit union and your members.

As a trusted financial partner, your credit union can play a vital role in encouraging and facilitating effective estate planning for your members. Helping them understand the importance of having a plan in the first place, providing a clear view of their options, and then helping make it happen are all crucial inflection points in which credit unions can play a role for their members.

Of course, you don’t have to go it alone. Consider integrating a robust, comprehensive estate planning platform into your shop’s digital financial planning and wellness offerings or provide it as a stand-alone service.

The younger generation of members and potential members are already showing a growing interest in estate planning and they’re also digital natives, who will expect to do as much as they can on their own and online.

The older crowd, too, are used to doing more and more online since COVID and increasingly open to using such a digital platform to create and maintain legally valid wills and trusts.

The benefits include:

  • Peace of mind for members: Providing tools for legacy planning gives your members peace of mind knowing their heirs and chosen causes will be gifted as the member chooses.
  • Enhanced member loyalty: By helping members secure their financial future, credit unions foster deeper, stickier relationships and long-term trust.
  • New revenue streams: As credit unions move away from overdraft and other fees, estate planning represents an opportunity to replace other declining non-interest income.
  • Increased digital engagement: Integrating estate planning services into your digital platforms can boost mobile app engagement and provide lead generation among high-net-worth members for your credit union’s wealth managers.

Choosing between a will and a trust is just the beginning. By actively educating members and empowering them to make wise choices while taking advantage of digital services, credit unions boost their own bottom line, deepen member relationships and trust, and, as importantly, better empower their members to build a secure and well-managed legacy.

All these things matter to today’s forward-looking credit union.

170M Americans need an estate plan. OneDigitalTrust offers a white-label, turnkey estate planning platform with pricing options tailored to the needs of individual credit unions and financial advisors.

Contact us today to learn more!